The U.S. Consumer:
Resilient in Aggregate,
Uneven Beneath the Surface
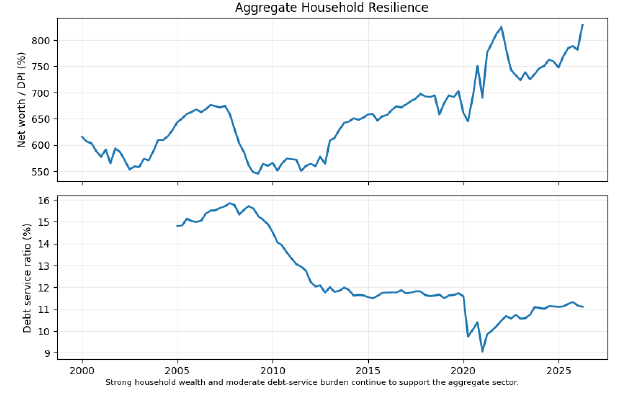
Measures of the aggregate U.S. household sector remain relatively strong. Household net worth stands near the upper end of its post-2000 range relative to disposable income, while the aggregate debt-service burden remains moderate. Consumer credit stress is elevated in several categories, but recent delinquency flows suggest more of a plateau than a renewed acceleration. Taken together, the headline data do not point to broad-based household financial deterioration.
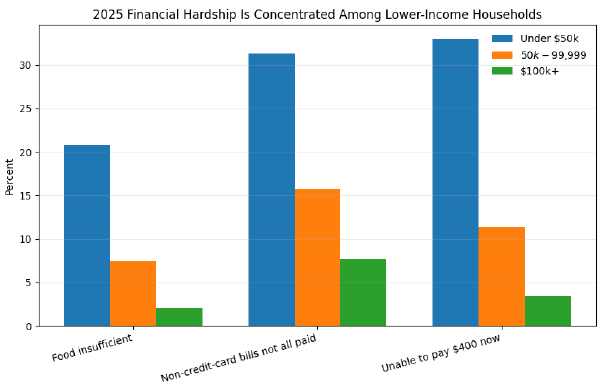
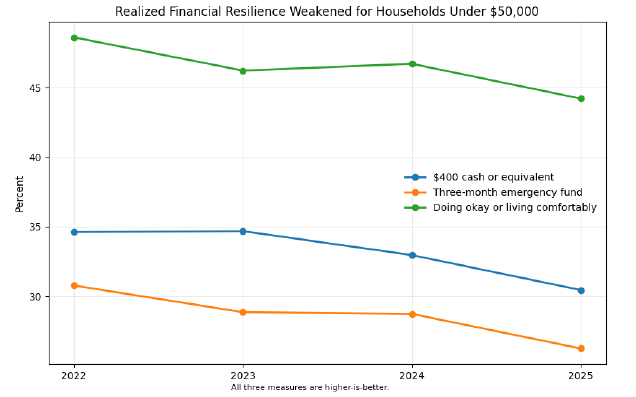
The distributional picture is much less comfortable. Federal Reserve survey data show a pronounced divide by income, with lower-income households reporting substantially less emergency liquidity and much greater difficulty meeting basic expenses. Among households earning less than $50,000, only 30% reported being able to cover a $400 emergency expense using cash or its equivalent in 2025, 26% had three months of emergency savings, and 44% described themselves as doing okay or living comfortably. All three measures declined from 2024. At the same time, food insufficiency rose to 21% and nearly one-third reported that they were unable to pay all non-credit-card bills in full.
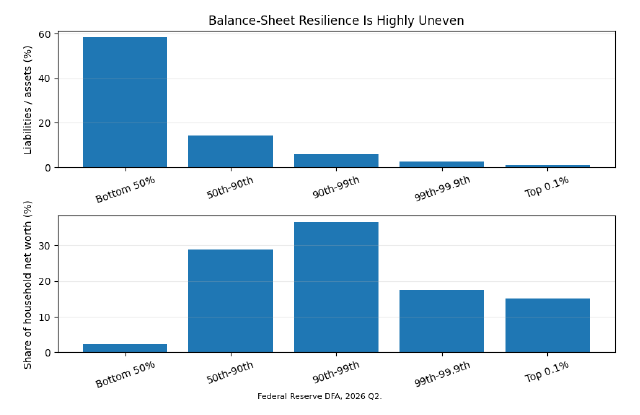
The divergence begins with household balance sheets. Aggregate wealth has benefited from rising financial-asset values, but those gains are not distributed evenly. The bottom 50% of households owns only about 2% of household net worth and carries liabilities equal to roughly 58% of assets, compared with much lower leverage among wealthier households. As a result, strong aggregate net-worth statistics provide only limited information about the financial resilience of households with fewer assets and less access to financial-market gains.
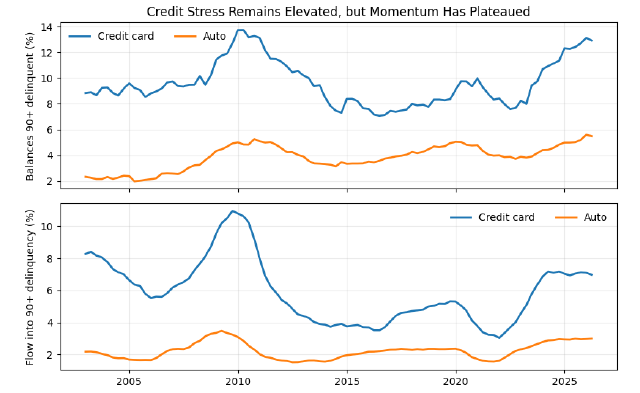
Credit data tell a related but somewhat more reassuring story. Credit-card and auto-loan serious delinquency rates remain elevated, but the rate at which balances are newly flowing into serious delinquency has generally stopped accelerating. As of the second quarter of 2026, approximately 12.9% of credit-card balances and 5.5% of auto balances were 90 or more days delinquent, while flows into serious delinquency were roughly 7.0% and 3.0%, respectively. We therefore view current credit conditions as stressed, but broadly plateauing rather than signaling a fresh deterioration.
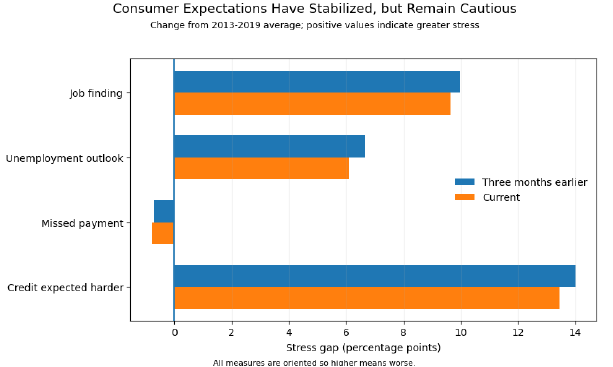
Forward-looking survey data add another layer. New York Fed Survey of Consumer Expectations measures remain cautious relative to their 2013–2019 averages, particularly for job-finding prospects, unemployment expectations and future credit availability. However, the latest three-month readings show modest improvement rather than further deterioration. That creates an interesting distinction between level and direction: household expectations remain weak by historical standards, but they have stabilized somewhat even though realized lower-income financial resilience deteriorated in the 2025 Survey of Household Economics and Decisionmaking.
For now, we think the evidence argues against characterizing the U.S. consumer as either uniformly “strong” or uniformly “weak.” Aggregate household capacity remains supportive, credit stress is elevated but not broadly accelerating, and the clearest weakness is concentrated among lower-income households. Whether the recent improvement in expectations becomes an early signal of better realized conditions—or simply a pause in an otherwise difficult environment—is something we will continue to monitor.
Survey of Consumer Finances (SCF)
Survey of Household Economics and Decisionmaking (SHED)
Distributional Financial Accounts (DFA)
Financial Accounts of the United States (Z.1)
 Comperio Retirement Consulting has been named one of the largest 100 Investment Consultants in the United States according to Pension & Investments (P&I) for the past 8 years